Where bitcoin fits in your money
“Don’t look for the needle in the haystack. Just buy the haystack!”John Bogle, founder of Vanguard, The Little Book of Common Sense Investing, 2007.This page in the book: yourbitcoinbasics.com/ch13
Bitcoin, right now
No price chart here on purpose. Chapter 6 covers price.
By the end of Chapter 13
Do it on your phone or laptop
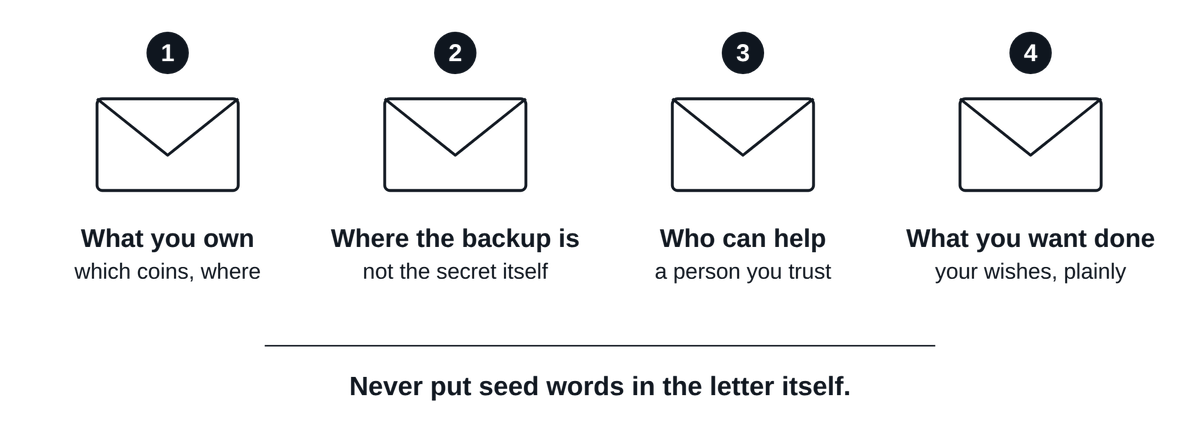
- Draft your recovery letter. Fifteen minutes, in a notes app or a document on your laptop. Write four short paragraphs, and leave out every secret.
- What you own and where. “I hold a small amount of bitcoin in an app called [name] on my phone, and a larger amount on a hardware wallet in my desk.” No amounts needed; they change.
- Where the backup is. “The 12-word phrase for the hardware wallet is in the fire safe in the hall closet, on a metal plate, in the envelope marked with my initials.” Do not write the words.
- Who can help. One name and one phone number, a person who knows how a wallet works and whom you trust. Tell them tonight.
- What you want done with it. One sentence.
- Print it. Put it where your other important papers live, and add one line to your will or trust that says the letter exists, when you next see your attorney. If you hold no bitcoin, do this for someone who does: ask them the four questions and see whether they can answer.
Did it stick?
Rate yourself: yes, mostly, or not yet. Not yet means reread that section. It does not mean you failed.
- I can name the things that come before bitcoin on an ordinary financial list, and say why my time horizon decides whether it belongs on the list at all.
- I can explain what a spot bitcoin ETF is, what a Bitcoin IRA gives up, and why someone might hold bitcoin both ways.
- I can state the one tax rule, name three taxable events and three that are not, and explain why the 1-year mark matters.
- I can list the four things my heirs need and say which one a will provides.
- I can say what I would do at a 50% fall, and where that answer is written down.
Your sister says, “I bought some bitcoin last year, and I’ve used it to pay for a few things online. It’s small, so I’m not going to bother mentioning it on my taxes.” What do you say?
Say your answer out loud first. Then open the model response.
Show the model response
Small does not make it tax-free. Spending bitcoin counts as selling it, so each purchase can create a gain or a loss, and the first page of Form 1040 asks whether you received, sold or spent digital assets. Platforms now send Form 1099-DA to you and to the IRS. Keep a record of what you paid and what each purchase was worth on the day. If the amounts are small, the tax may be small too, but report it. A CPA can sort out a year of it quickly.
The Part, in five sentences
- Know where your money sits and what it is exposed to before you add anything new.
- Start small, sign your volatility contract first, and if you buy, buy on a schedule you decided in advance.
- Higher on the custody ladder means more control, not more safety for everyone, and no one pays you back for lost self-custody.
- Every scam ends with the same request: send first, read back a code, type your words, or hurry.
- Spending bitcoin is a taxable sale, so keep records from the first purchase, and leave your heirs a plan they can follow.
“Isn’t all of this, the keys and the letters and the metal plates, a lot of work and risk for something I could just hold in a fund in my brokerage account like everything else I own?”
My answer
For many people, yes, and the fund is the right fit. If you want exposure to the price, you want one statement, and your heirs already know how to deal with a brokerage, the fund does that with the fewest new habits. I would never tell someone that was the wrong choice.
What the fund does not give you is what the earlier chapters were about. You cannot send fund shares to a daughter abroad in 10 minutes on a Sunday. You cannot hold them outside a system that once refused James an account. Your claim runs through a fund company, a custodian, and a market that closes on weekends, and if any of those has a bad day, so do you. The fund is bitcoin’s price without bitcoin’s properties. Holding your own keys is the reverse: all the properties, and all the responsibility, including the tax records and the letter.
Those are different products for different purposes, and plenty of people hold some of each. The objection is fair as far as it goes. It only stops being fair when it claims the two are the same thing.
Want a second opinion with sources? The Bitcoin Evidence Base answers claims like this one.
Watch, read, explore
Digital assets and your taxes
What the IRS asks, including the question on the front of Form 1040.irs.govExplore · 10 minNakamoto Portfolio
See what a small slice in bitcoin did to an ordinary mix of stocks and bonds over any period.Swan (a company that sells bitcoin)Products and services named are examples, not recommendations. I have no financial relationship with any of them.
The 26 notes for Chapter 13
- Peak-to-trough declines and time to a new high, computed from Coin Metrics Community Network Data, daily bitcoin reference price (PriceUSD), coinmetrics.io, retrieved September 2026: June 2011 high to November 2011 low, 93%, new high February 2013; December 2013 to January 2015, 84%, new high February 2017; December 2017 to December 2018, 84%, new high November 2020; November 2021 to November 2022, 77%, new high March 2024.
- Nakamoto Portfolio, a Swan Research project, nakamotoportfolio.com, retrieved September 2026. Allocation ranges: BlackRock Investment Institute, “Sizing Bitcoin in Portfolios,” December 12, 2024, blackrock.com; Morgan Stanley Global Investment Committee, October 2025, as reported by CNBC, October 2025; Bank of America, Chief Investment Office guidance effective January 5, 2026, as reported by The Block, December 2, 2025, theblock.co; all retrieved October 2026.
- U.S. Securities and Exchange Commission, “Statement on the Approval of Spot Bitcoin Exchange-Traded Products,” January 10, 2024.
- iShares Bitcoin Trust ETF (IBIT), sponsor fee 0.25%, ishares.com, retrieved September 2026; Fidelity Wise Origin Bitcoin Fund (FBTC), expense ratio 0.25%, fund fact sheet, Fidelity, June 2026. The spot bitcoin ETFs are organized as grantor trusts rather than as funds under the Investment Company Act, which is why a share is a claim on the trust’s bitcoin and why sales are reported on Form 1099-B.
- IRS, Publication 590-B, Distributions from Individual Retirement Arrangements (IRAs), for use in preparing 2025 returns, “What Are Qualified Distributions?”, irs.gov, retrieved September 2026.
- iTrustCapital, pricing page, 1% per crypto trade and no monthly or annual fee on standard accounts, itrustcapital.com, retrieved September 2026; Swan Bitcoin, IRA fee schedule, 1% per trade plus a monthly fee of 0.02% of assets with a $20 minimum, swanbitcoin.com, retrieved September 2026.
- Internal Revenue Code section 408(a)(2), and IRS, Publication 590-A, Contributions to Individual Retirement Arrangements (IRAs), for use in preparing 2025 returns: “The trustee or custodian must be a bank, a federally insured credit union, a savings and loan association, or an entity approved by the IRS to act as trustee or custodian,” irs.gov, retrieved September 2026; McNulty v. Commissioner, 157 T.C. 79 (2021), holding that an IRA owner who took personal possession of the account’s assets took a taxable distribution.
- IRS, Notice 2014-21, 2014.
- IRS, “Digital Assets,” irs.gov/digitalassets, and Frequently Asked Questions on Virtual Currency Transactions, 2025.
- IRS, Revenue Procedure 2024-40, section 2503 annual exclusion of $19,000 for calendar year 2025; IRS, Revenue Procedure 2025-32, October 9, 2025, $19,000 for calendar year 2026, irs.gov, retrieved September 2026.
- IRS, Topic No. 409, Capital Gains and Losses; IRS, Revenue Procedure 2024-40, maximum zero rate amount for unmarried individuals of $48,350 for 2025; IRS, Revenue Procedure 2025-32, $49,450 for 2026, irs.gov, retrieved September 2026.
- Internal Revenue Code section 1091 (wash sales). Proposals to extend it to digital assets include Senator Cynthia Lummis’s digital asset tax bill, press release, July 3, 2025, and H.R. 10357, the Digital Asset Tax Certainty Act, described in Joint Committee on Taxation, JCX-47-26, September 14, 2026, and approved by the House Ways and Means Committee on September 16, 2026. As of September 2026, none had been enacted.
- Celsius Network, Chapter 11 petition, July 2022; BlockFi, Chapter 11 petition, November 2022, U.S. Bankruptcy Court filings.
- IRS, Form 1040 instructions, digital asset question, tax year 2025.
- IRS, Treasury Decision 10000, “Gross Proceeds and Basis Reporting by Brokers and Determination of Amount Realized and Basis for Digital Asset Transactions,” June 2024: gross proceeds reporting for transactions on or after January 1, 2025, basis reporting for covered digital assets acquired and sold on or after January 1, 2026; IRS, “Final regulations and related IRS guidance for reporting by brokers on sales and exchanges of digital assets,” and Instructions for Form 1099-DA (2026), irs.gov, retrieved September 2026.
- Jeff John Roberts and Nicolas Rapp, “Exclusive: Nearly 4 Million Bitcoins Lost Forever, New Study Says,” Fortune, November 25, 2017, reporting Chainalysis estimates of 2.78 to 3.79 million; River Intelligence, “How Much Bitcoin Is Gone Forever?”, September 6, 2023 (3 to 4 million), river.com; Dhruv Bansal, “The Geology of Lost Coins,” Unchained, updated April 17, 2026 (3.0 to 3.8 million), unchained.com, retrieved September 2026.
- Coinbase Help Center, “Claim a decedent’s Coinbase account,” help.coinbase.com, retrieved September 2026.
- Internal Revenue Code section 1014, basis of property acquired from a decedent; IRS, Publication 551, Basis of Assets, revised December 2025, “Inherited Property,” irs.gov, retrieved September 2026.
- Nunchuk, “Inheritance Planning,” nunchuk.io/inheritance, and “Nunchuk 2.0: Autonomous Inheritance,” November 12, 2025, nunchuk.io; Casa, “Casa Inheritance,” casa.io/inheritance, retrieved September 2026.
- Centers for Disease Control and Prevention, National Center for Health Statistics, “Mortality in the United States, 2024,” NCHS Data Brief No. 548, January 2026: life expectancy at birth of 81.4 years for females and 76.5 years for males, a difference of 4.9 years.
- Kahneman and Tversky, “Prospect Theory: An Analysis of Decision under Risk,” Econometrica, 1979.
- Drawdowns computed from Coin Metrics Community Network Data, daily bitcoin reference price (PriceUSD), coinmetrics.io, retrieved September 2026: December 2017 high to December 2018 low, 84%; November 2021 high to November 2022 low, 77%.
- Gollwitzer, “Implementation Intentions: Strong Effects of Simple Plans,” American Psychologist, 1999.
- Andreas M. Antonopoulos and David A. Harding, Mastering Bitcoin, 3rd ed., O’Reilly, 2023, chapter 4, on the 20-byte (160-bit) hash that standard pay-to-public-key-hash and native segwit addresses commit to; 2 to the 160th power is about 1.46 times 10 to the 48th, a 49-digit number.
- Federal Housing Finance Agency, Director William Pulte, directive to Fannie Mae and Freddie Mac on considering cryptocurrency as a reserve asset in single-family mortgage risk assessments, June 25, 2025, fhfa.gov, retrieved September 2026.
- Internal Revenue Code section 1014 (basis of property acquired from a decedent); IRS Publication 551, Basis of Assets, on the fair-market-value basis of inherited property, irs.gov, retrieved September 2026.
Found a broken link or a mistake? Write to ybbook@proton.me and I will fix it.